Imagine you are running a manufacturing business in Ogun State, near Lagos. You are currently operating at 70% capacity, and suddenly a large supermarket chain knocks on your door with a special offer. They want 20,000 buckets, but at a reduced price. Do you take the deal?
This is exactly the scenario Toyin Plastics faces. It is a classic decision that business owners and managers encounter regularly. Should you accept an order that appears less profitable than your regular sales? Does the reduced price still make sense once you understand your cost structure?
Many Nigerian manufacturers struggle with these decisions daily. Without proper cost analysis, businesses either reject profitable opportunities or accept unprofitable contracts that erode their bottom line.
In this post, we will walk through the decision making process using marginal costing principles. We will show you exactly how Toyin Plastics arrived at their decision and why understanding contribution margins is essential for every manufacturing business.
Understanding the Toyin Plastics Scenario
Toyin Plastics manufactures buckets in Ogun State, near Lagos. The company currently operates at 70% capacity, producing 70,000 units. Their regular selling price is ₦1,400 per bucket.
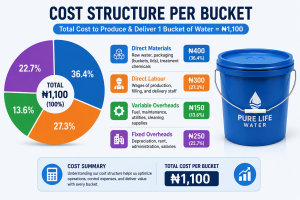
Cost Structure per Bucket
Cost Component
Amount (₦)
Direct Materials
400
Direct Labour
300
Variable Factory Overheads
150
Fixed Factory Overheads
250
Total Cost
1,100
At first glance, the total cost of ₦1,100 per bucket suggests that the business earns a profit of ₦300 per unit at the regular selling price of ₦1,400.
The Special Offer
A large supermarket chain in Lagos offers to buy 20,000 buckets at a reduced price of ₦1,000 per bucket. This is ₦400 below the regular selling price and ₦100 below the total cost per unit.
Based on total cost accounting, this offer would appear to generate a loss of ₦100 per bucket, or ₦2,000,000 in total. A manager using total cost thinking would likely reject the offer.
The good news is that they will collect the goods from the factory themselves, meaning no additional selling or distribution costs. This eliminates any concerns about increased delivery expenses.
But is the offer truly unprofitable? Let us examine it through the lens of marginal costing.
What is Marginal Costing?
Marginal costing is a management accounting technique that distinguishes between fixed and variable costs for decision making purposes. Under this approach, only variable costs are charged to products, while fixed costs are treated as period costs and written off against the contribution of the period.
This technique is particularly valuable for short term decision making because it reveals the incremental impact of business choices. Unlike absorption costing, which allocates fixed overheads to products, marginal costing focuses on the behaviour of costs in relation to changes in activity levels.
For manufacturing businesses like Toyin Plastics, marginal costing provides clarity on whether accepting additional orders will increase or decrease overall profitability. It helps managers see beyond the total cost figure to understand the true incremental impact of their decisions.
The fundamental principle of marginal costing is that fixed costs do not change with production volume. They remain constant within a relevant range of activity. Therefore, when evaluating a special order, the only costs that matter are those that will increase as a direct result of accepting the order. These are the variable costs.
Key Assumptions of Marginal Costing
Before applying marginal costing to the Toyin Plastics decision, it is important to understand the assumptions that underpin this technique:
Constant Variable Cost per Unit
Variable costs remain constant per unit regardless of production volume. In the Toyin Plastics case, direct materials, direct labour, and variable overheads are assumed to be ₦850 per bucket regardless of how many units are produced.
Fixed Costs Remain Unchanged
Fixed costs do not change within the relevant range of activity. The ₦250 fixed overhead per bucket at 70,000 units represents an allocation, not an incremental cost.
Selling Price Remains Constant
For the purpose of the decision, the special order price of ₦1,000 per bucket is considered fixed. Any changes in selling price would require separate analysis.
Capacity is Available
The business has sufficient spare capacity to produce the additional units without incurring extra fixed costs. Toyin Plastics operates at 70% capacity, meaning they have room for 20,000 more units.
Costs Can be Clearly Classified
All costs must be clearly identifiable as either fixed or variable. This is why understanding your cost structure is essential for effective marginal costing.
a) Marginal Cost (Variable Cost) per Bucket
Marginal costing focuses on the costs that actually change with production volume. For Toyin Plastics, these costs are:
Cost Component
Amount (₦)
Direct Materials
400
Direct Labour
300
Variable Factory Overheads
150
Marginal Cost per Bucket
850
The fixed factory overheads (₦250) are not included in marginal cost because they do not change with production volume. Whether Toyin Plastics produces 70,000 units or 90,000 units, the total fixed overhead remains the same. The ₦250 allocation is simply an accounting distribution to spread fixed costs across units produced.
Why Marginal Cost is the Correct Figure for Decision Making
When evaluating a special order, the relevant cost is the additional cost that will be incurred to produce the extra units. For Toyin Plastics, this is ₦850 per bucket. This represents the cash outflow directly attributable to producing one more bucket.
The fixed overhead of ₦250 per bucket would be incurred regardless of whether the special order is accepted. It is not an incremental cost and should therefore be excluded from the decision calculation.
b) Contribution Analysis and Decision
Contribution is the difference between selling price and variable cost. It represents the amount available to cover fixed costs and generate profit.
Contribution per Bucket (Regular Sales)
Contribution = Selling Price minus Variable Cost
Contribution = ₦1,400 minus ₦850 = ₦550 per bucket
This means that for every bucket sold at the regular price of ₦1,400, Toyin Plastics generates ₦550 to cover fixed costs and contribute to profit. With fixed costs of ₦250 per bucket (allocated), the profit per bucket at regular sales is ₦300.
Contribution per Bucket (Special Order)
Contribution = Special Price minus Variable Cost
Contribution = ₦1,000 minus ₦850 = ₦150 per bucket
Although this is significantly lower than the regular contribution of ₦550, every naira of contribution improves the company’s bottom line because fixed costs have already been covered by regular operations.
Total Contribution from the Special Order
₦150 multiplied by 20,000 buckets = ₦3,000,000
This ₦3,000,000 is the additional profit that Toyin Plastics would earn from accepting the special order.
Decision: Toyin Plastics SHOULD Accept the Special Offer
Why the Offer Should Be Accepted:
Positive Contribution
The order generates a positive contribution of ₦150 per bucket. Any contribution above zero improves profitability when there is spare capacity.
Additional Profit of ₦3,000,000
This order would increase total profit by ₦3,000,000 without any increase in fixed costs. This is money that would otherwise be left on the table.
Spare Capacity
The company is operating at only 70% capacity. Producing 20,000 additional buckets does not require additional factory space, machinery, or fixed overheads. The idle capacity is currently generating no revenue.
No Additional Selling or Distribution Costs
The supermarket chain is collecting the goods from the factory. This means no delivery costs, no sales commissions, and no additional selling expenses.
Fixed Costs Remain Unchanged
The ₦17,500,000 in fixed factory overheads (70,000 units × ₦250) would be incurred whether the order is accepted or not. Fixed costs do not change with production volume within the relevant range.
The Key Insight
The special order does not need to cover fixed costs because those costs would exist whether the order is accepted or not. The relevant question is whether the incremental revenue exceeds the incremental cost. In this case, it clearly does.
The Concept of Contribution Margin and Its Importance
Contribution margin is one of the most important concepts in management accounting. It represents the amount of revenue that remains after deducting variable costs, and it is used to cover fixed costs and generate profit.
The contribution margin formula is:
Contribution = Sales Revenue minus Variable Costs
Why Contribution Margin Matters
Pricing Decisions
Understanding contribution margin helps businesses set prices that maximise profitability. If you know your variable cost per unit, you can determine the minimum price you can accept for a special order.
Product Mix Decisions
When a business produces multiple products, contribution margin analysis helps determine which products to promote and which to discontinue.
Profit Planning
Contribution margin is the foundation for break even analysis and profit planning. It helps businesses understand how many units must be sold to cover costs and achieve target profits.
Performance Measurement
Contribution margin is a better performance metric than profit for evaluating individual products or business segments because it removes the impact of arbitrary overhead allocations.
Contribution Margin Ratio
The contribution margin ratio is contribution divided by sales revenue. For Toyin Plastics:
Regular sales contribution margin ratio = ₦550 ÷ ₦1,400 = 39.3%
Special order contribution margin ratio = ₦150 ÷ ₦1,000 = 15%
Although the special order has a lower contribution margin ratio, it still makes a positive contribution to covering fixed costs and generating profit.
c) Why Fixed Factory Overheads (₦250) Are Ignored
From a marginal costing perspective, fixed factory overheads are excluded from the decision for several crucial reasons:
Focus on Relevant Costs
Marginal costing emphasises additional costs and revenues that directly result from a decision. Fixed overheads do not change. They remain constant regardless of whether this special order is accepted.
In the Toyin Plastics case, the total fixed factory overhead of ₦17,500,000 (₦250 × 70,000 units) remains unchanged whether the company produces 70,000 units or 90,000 units. The allocation of ₦250 per bucket is simply an accounting convention, not a real incremental cost.
Sunk Cost Principle
Fixed costs are already sunk or committed. They would be incurred even if the special order is declined. Fixed costs represent past commitments such as long term lease agreements, depreciation on machinery, and salaries of permanent staff.
These costs cannot be avoided by rejecting the special order. Therefore, they should not influence the decision.
Capacity Considerations
At 70% capacity, Toyin Plastics has room to produce 20,000 more buckets without needing to increase fixed costs. The company already has the factory space, machinery, and supervisory staff in place.
If the company were operating at full capacity, accepting the special order might require additional fixed costs such as new machinery or overtime payments. In that case, the decision might be different.
Short Term Decision Focus
For one off decisions, the only relevant costs are those that change. Fixed overheads are period costs, not product costs in the decision context.
This does not mean fixed costs are irrelevant in all decisions. They are crucial for long term pricing decisions, capacity expansion decisions, and investment decisions. But for a one time special order, they are not relevant.
Avoids Arbitrary Allocations
Allocating fixed overheads to products involves arbitrary assumptions about how fixed costs should be shared among products or production volumes.
In the Toyin Plastics case, the ₦250 allocation assumes that fixed overheads should be spread equally across all 70,000 units. But if production increases, the allocation per unit would change. Using allocations in decision making can lead to incorrect conclusions.
Marginal Costing vs Absorption Costing: A Comparison
Understanding the difference between marginal costing and absorption costing is essential for proper decision making.
Absorption costing allocates fixed overheads to products, which can lead to misleading conclusions in short term decisions.
In the Toyin Plastics case, absorption costing would show a loss of ₦100 per bucket on the special order (₦1,000 selling price minus ₦1,100 total cost). A manager using absorption costing would likely reject the offer, losing ₦3,000,000 in potential profit.
This demonstrates why marginal costing is superior for short term decision making.
When Absorption Costing is Appropriate
Absorption costing is required for external financial reporting under accounting standards such as IFRS and Nigerian GAAP. It is also appropriate for long term pricing decisions where all costs must be recovered over time.
For short term decisions, however, marginal costing provides clearer and more useful information.
When to Use Marginal Costing in Business Decisions
Marginal costing is particularly useful for the following types of business decisions:
Special Order Decisions
When a customer offers to buy products at a reduced price, marginal costing helps determine whether the order will increase profitability.
Make or Buy Decisions
When deciding whether to manufacture a component internally or purchase it from an external supplier, marginal costing highlights the relevant costs.
Product Discontinuation Decisions
When considering whether to discontinue a product, marginal costing reveals the product’s contribution to covering fixed costs.
Export Pricing Decisions
When pricing products for export markets, marginal costing helps determine the minimum acceptable price.
Plant Closure Decisions
When considering whether to close a plant or department, marginal costing identifies the costs that would be avoided.
Capacity Utilisation Decisions
When deciding whether to increase or decrease production, marginal costing shows the impact on profit.
Pricing Decisions
When setting prices, understanding contribution margin helps identify the relationship between price, volume, and profitability.
Factors to Consider Beyond the Numbers
While the numbers suggest acceptance, prudent managers consider several qualitative factors:
Impact on Regular Customers
Will offering a lower price to the supermarket chain upset existing customers who pay full price? Some customers may demand similar discounts if they discover the lower price.
Brand Positioning
Does accepting a reduced price undermine the perceived value of your products? For premium brands, discount pricing can damage brand equity.
Future Pricing Expectations
Will the supermarket chain expect the same discount on future orders? Once a customer receives a discount, they often expect it to continue.
Production Capacity
Can you fulfil the order without disrupting regular production? Accepting the order should not compromise quality or delivery times for existing customers.
Opportunity Cost
Could the capacity be used for more profitable orders? If the special order uses capacity that could be sold at regular prices, the opportunity cost must be considered.
Relationship Building
Could this order lead to a long term relationship with a major customer? The supermarket chain may become a valuable ongoing customer.
Industry Competition
If you decline the order, will a competitor accept it and strengthen their position in the market?
Legal and Contractual Obligations
Are there any restrictions on selling at reduced prices? Some suppliers impose minimum pricing requirements.
In the Toyin Plastics case, the 30% spare capacity makes this a low risk decision. However, every business must evaluate these factors before committing.
Common Mistakes in Pricing Decisions
Many businesses fall into these traps when evaluating special orders:
Mistake 1: Including Fixed Costs in Short Term Decisions
Fixed costs do not change with the decision and should be excluded from marginal analysis. Including them leads to rejecting profitable opportunities.
Mistake 2: Ignoring Opportunity Costs
Using capacity for one order may mean missing out on another opportunity. Consider whether the capacity could be used for more profitable purposes.
Mistake 3: Failing to Consider Incremental Costs
Some costs may increase if the order requires overtime, additional setup time, or expedited shipping. Identify all incremental costs before making a decision.
Mistake 4: Overlooking Strategic Implications
Price reductions today may establish expectations that are difficult to reverse. Consider the long term implications before accepting a lower price.
Mistake 5: Incomplete Cost Analysis
Not all variable costs are obvious. Consider utilities, consumables, and maintenance that may vary with production. Also consider increased wear and tear on machinery.
Mistake 6: Treating All Fixed Costs as Irrelevant
While fixed costs are irrelevant in the short term, some fixed costs may become variable over a longer time horizon. For example, if the special order requires additional factory space, a new lease would be an incremental cost.
Mistake 7: Confusing Contribution with Profit
Contribution is not the same as profit. While contribution is useful for decision making, managers must ensure that total contribution across all products covers total fixed costs.
Break Even Analysis and Margin of Safety
Understanding break even points adds depth to the decision making process.
Break Even Point
The break even point is the level of sales at which total revenue equals total costs, resulting in zero profit.
For Toyin Plastics:
Total Fixed Costs = 70,000 units × ₦250 = ₦17,500,000
Break Even Point (units) = Total Fixed Costs ÷ Contribution per Unit
Break Even Point = ₦17,500,000 ÷ ₦550 = 31,818 units
This means Toyin Plastics must sell at least 31,818 buckets at the regular price of ₦1,400 to cover all fixed costs.
Margin of Safety
Margin of safety is the difference between actual sales and break even sales. It indicates how much sales can decline before the business starts making losses.
Current Sales = 70,000 units
Break Even Sales = 31,818 units
Margin of Safety = 70,000 minus 31,818 = 38,182 units
Margin of Safety Ratio = 38,182 ÷ 70,000 = 54.5%
This means Toyin Plastics can afford a 54.5% decline in sales before making a loss. This is a comfortable position.
Impact of the Special Order on Break Even
If Toyin Plastics accepts the special order:
Total Production = 90,000 units
Total Contribution = (70,000 × ₦550) + (20,000 × ₦150) = ₦38,500,000 + ₦3,000,000 = ₦41,500,000
Total Fixed Costs = ₦17,500,000
Profit = ₦41,500,000 minus ₦17,500,000 = ₦24,000,000
The special order increases profit from ₦21,000,000 (70,000 × ₦300) to ₦24,000,000, an increase of ₦3,000,000.
How MOC Accountants Can Transform Your Business Decisions
At MOC Accountants, we do not just audit numbers. We transform decision making.
Our team of experienced management accountants and auditors helps businesses like yours navigate complex financial decisions with confidence.
Our Services
Cost Analysis and Optimisation
Understand your true cost structures and identify hidden savings across your operations. We help you distinguish between fixed and variable costs so you can make better pricing decisions.
Pricing Strategy Support
Make data driven pricing decisions that maximise profitability without sacrificing market share. We help you determine the minimum acceptable price for special orders and export contracts.
Decision Support Systems
Implement robust management reporting that guides strategic choices with clarity. We design dashboards and reports that highlight contribution margins and profitability drivers.
Capacity Planning
Optimise production decisions with clear contribution analysis that reveals profitable pathways. We help you determine when to accept additional orders and when to say no.
Financial Modelling
Build models that answer “what if” scenarios before you commit resources. We help you evaluate the financial impact of strategic decisions.
Management Accounting Training
Equip your team with marginal costing and decision making skills that stick. We provide practical training that your team can apply immediately.
Budgeting and Forecasting
Plan with confidence using accurate variable cost analysis that drives realistic projections. We help you build budgets that reflect your true cost structure.
Audit and Assurance
We provide comprehensive audit services that ensure your financial statements are accurate and compliant with regulatory requirements.
Industries We Serve
Manufacturing
We understand the unique challenges facing Nigerian manufacturers. From cost analysis to pricing strategies, we provide practical solutions that improve profitability.
Retail and Distribution
We help retailers and distributors understand their contribution margins and optimise their product mix.
Construction and Real Estate
We provide financial analysis and decision support for construction companies and property developers.
Professional Services
We help professional service firms understand their cost structures and price their services profitably.
Non Profit Organisations
We provide financial management and reporting services for NGOs and charitable organisations.
Our Approach
Understand Your Business
We take time to understand your operations, industry, and competitive environment before making recommendations.
Analyse Your Numbers
We perform detailed financial analysis to identify opportunities and risks.
Provide Practical Recommendations
We offer actionable recommendations that you can implement immediately.
Support Implementation
We work alongside your team to ensure successful implementation of our recommendations.
Measure Results
We help you track the impact of our recommendations and make adjustments as needed.
Frequently Asked Questions about Marginal Costing
What is marginal cost per unit?
Marginal cost per unit is the additional cost incurred to produce one more unit. It includes all variable costs such as direct materials, direct labour, and variable overheads. Fixed costs are not included because they do not change with production volume.
How do you calculate contribution per unit?
Contribution per unit is calculated by subtracting variable cost per unit from selling price per unit. For example, if selling price is ₦1,000 and variable cost is ₦850, the contribution per unit is ₦150.
Should I accept a special order below total cost?
If the special order price exceeds marginal cost and you have spare capacity, accepting the order will increase overall profit. Fixed costs are irrelevant to this decision because they would be incurred regardless.
What is the difference between marginal costing and absorption costing?
Marginal costing treats fixed costs as period costs and does not allocate them to products. Absorption costing allocates fixed costs to products. Marginal costing is better for short term decisions, while absorption costing is required for external financial reporting.
When should businesses use marginal costing?
Marginal costing is ideal for special order decisions, make or buy decisions, product discontinuation analysis, pricing decisions, and capacity utilisation decisions.
How does contribution margin help with pricing?
Understanding contribution margin helps businesses determine the minimum price they can accept for a product or order. Any price above variable cost contributes to covering fixed costs and generating profit.
What is the relevant range in marginal costing?
The relevant range is the range of activity within which fixed costs remain constant. Outside this range, fixed costs may change, and the analysis would need to be adjusted.
Can marginal costing be used for long term decisions?
Marginal costing is primarily used for short term decisions. For long term decisions, all costs including fixed costs must be considered. Absorption costing is more appropriate for long term pricing and investment decisions.
How do I know if my costs are fixed or variable?
Fixed costs remain constant regardless of production volume. Examples include rent, salaries, and depreciation. Variable costs change with production volume. Examples include materials, direct labour, and utilities that vary with production.
What is the difference between contribution and profit?
Contribution is sales revenue minus variable costs. Profit is contribution minus fixed costs. Contribution measures the amount available to cover fixed costs, while profit is the amount remaining after all costs are covered.
Final Takeaway
Marginal costing reveals that the special order from the supermarket chain would generate an additional ₦3,000,000 in profit without increasing fixed costs.
The reduced price of ₦1,000 might seem unprofitable when looking at total costs, but it is a winning proposition when analysed correctly.
Always remember: In short term decision making, focus on incremental costs and revenues. Make decisions based on contribution, not total cost.
Understanding your cost structure and applying marginal costing principles can transform your business decisions and significantly improve profitability.
Let Us Have a Conversation
Do not let poor decision making drain your profits. Whether you are considering a special order, launching a new product, or planning capacity expansion, we will help you see the full picture.
Our Promise: We will help you uncover at least one decision making improvement that pays for our fees many times over.
Book a complimentary 30 minute consultation. Let us review one of your recent business decisions and see if marginal costing would have changed the outcome.
Share This Post
Found this case study helpful? Share it with a fellow business owner or manager who might be facing a similar decision. Drop a comment below and tell us what special offers you have had to evaluate in your business.
Taiwo Sowunmi is an avid blogger who enjoys blogging finance and accounting related advisory to businesses. Follow this blog for more insights on management accounting, financial decision making, and strategic business advisory from MOC Accountants.




There are no comments